


👋 Hey, Sahil here - Welcome back to Venture Curator, where we explore how top investors think, how real founders build, and the strategies shaping tomorrow’s companies.
Big idea + report of the week :
Do you really need revenue to raise a seed round, or are founders overthinking it?
The AI categories VCs are overpaying for right now.
Frameworks & insightful posts :
The Billion-Dollar Founder Study: What 20 years of unicorns say about who you should build with.
Are you overpaying your first hire with equity without realising it?
Are waitlists still worth building in 2026: a16z Guide?
FROM OUR PARTNER - FRAMER
🚀 Launch fast. Design beautifully. Build your startup on Framer — free for your first year.

First impressions matter. With Framer, early-stage founders can launch a beautiful, production-ready site in hours. No dev team, no hassle. Join hundreds of YC-backed startups that launched here and never looked back.
Pre-seed and seed-stage startups new to Framer can enjoy:
One year free: Save $360 with a full year of Framer Pro, free for early-stage startups.
No code, no delays: Launch a polished site in hours, not weeks, without hiring developers.
Built to grow: Scale your site from MVP to full product with CMS, analytics, and AI localisation.
Join YC-backed founders: Hundreds of top startups are already building on Framer.
Apply to claim your free year →
🤝 PARTNERSHIP WITH US
Get your product in front of over 115,000+ audience - Our newsletter is read by thousands of tech professionals, founders, investors and managers worldwide. Get in touch today.
START WITH
🧠 Big idea + report of the week
Do you really need revenue to raise a seed round, or are founders overthinking it?
Most founders assume there’s a clear benchmark.
Hit $1M ARR → raise
Hit $500K ARR → maybe raise
Below that → not ready
But this data shows something very different.
Silicon Valley Bank’s latest report (2024–2025 U.S. tech companies) puts the median seed-stage revenue at ~$220K. Sounds reasonable, until you look deeper.
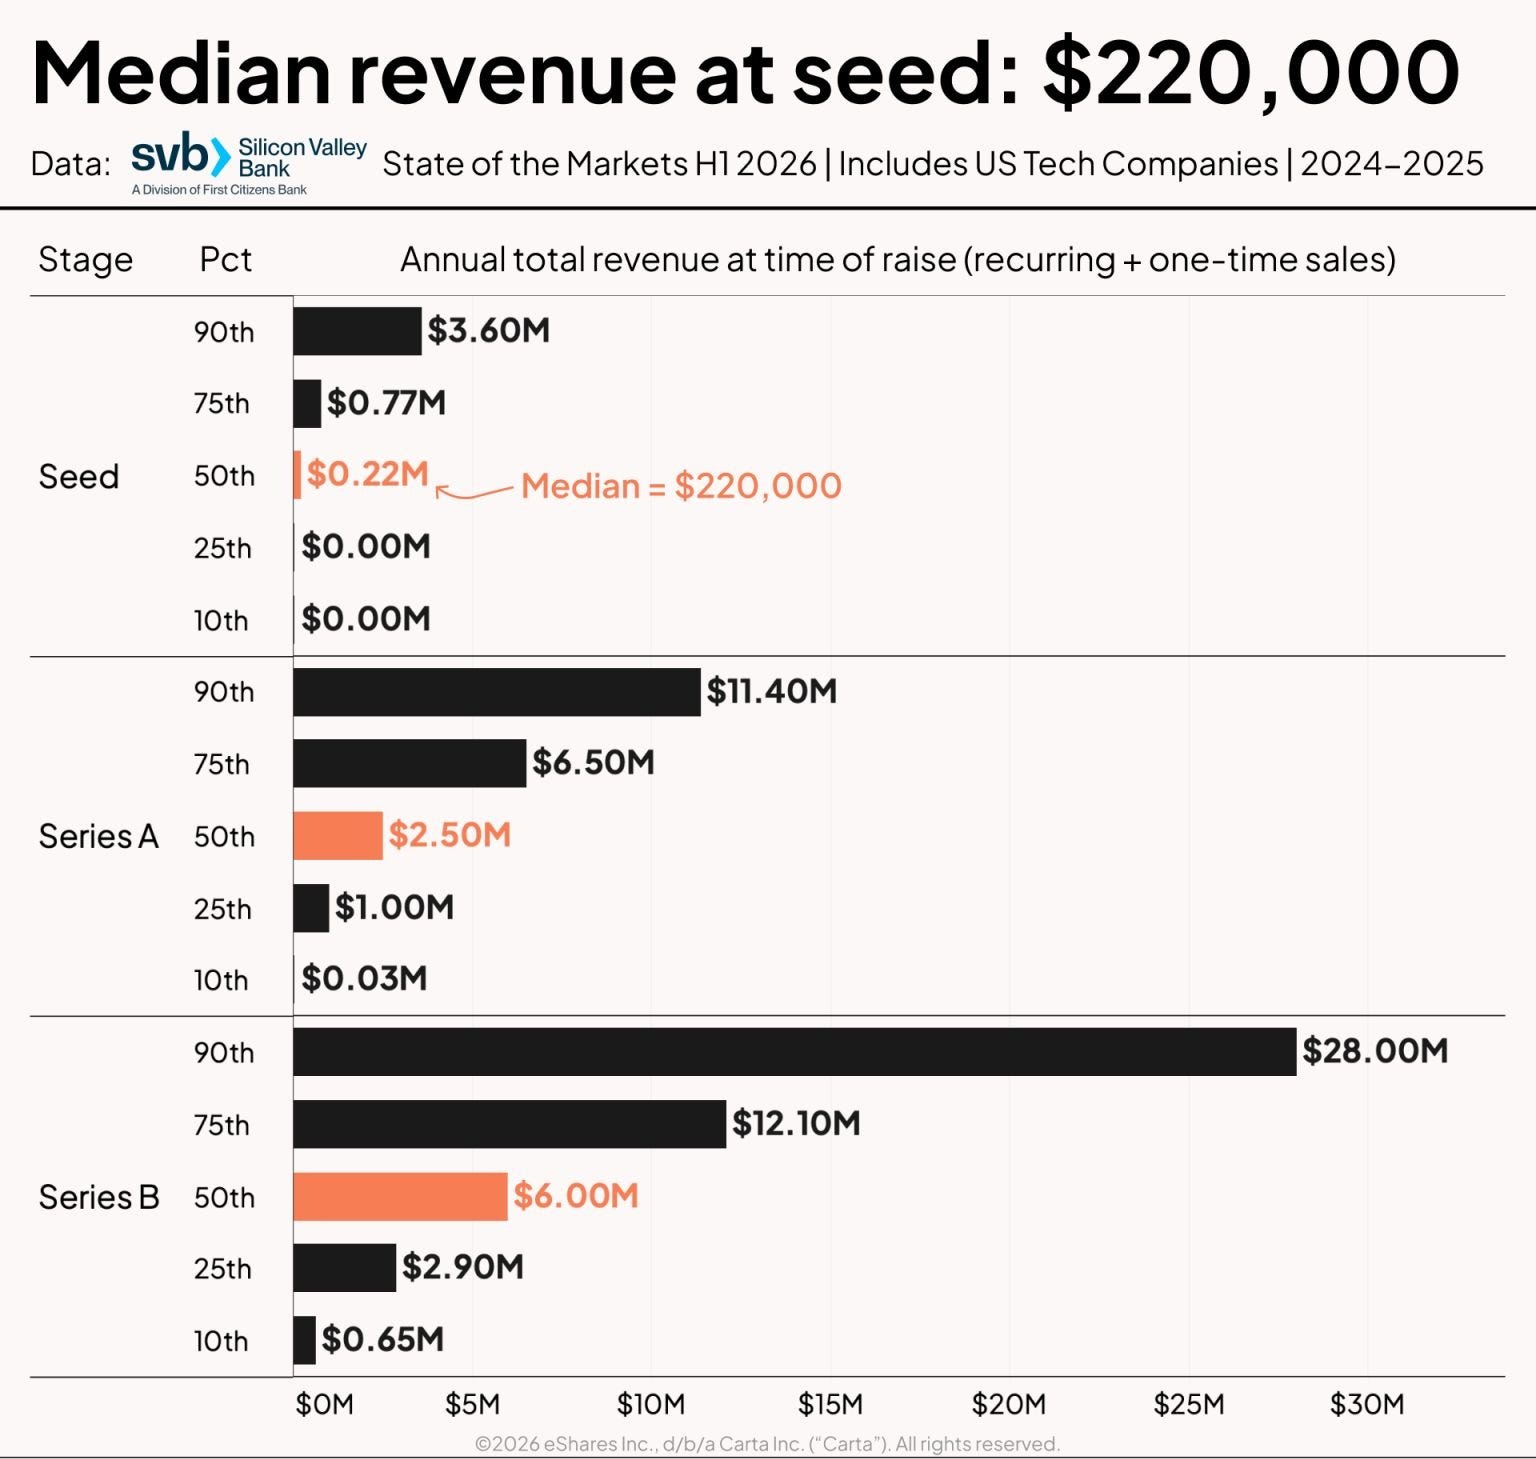
Because there is no single number. Revenue at seed is completely spread out:
Some companies start with $0 revenue
Many sit around $200K–$300K
Strong ones push toward $700K+
Outliers go all the way to $3M+
Same round. Completely different starting points.
That’s the first shift founders need to understand:
You’re not being evaluated on a fixed threshold. You’re being evaluated on trajectory and belief.
And that’s why comparing yourself to what you see online quietly kills momentum. Most of the companies you hear about sit in the top 10%. They are not the market; they are the exception.
The second, more important insight shows up when you track what happens after the seed.
The jump required between rounds is where things get real:
Seed median → ~$220k
Series A median → ~$2.5M
Series B median → ~$6M
This is not gradual growth.
It’s a sharp expectation of acceleration. Which means:
You can raise seed without much revenue, but you cannot drift into Series A. The real pressure starts the moment you raise.
Especially in AI, this gap is becoming even more intense. A lot of seed rounds today are going to:
Pre-revenue founders
Fast-moving technical teams
Products with early signals but no strong monetisation yet
But that also compresses time. You’re expected to go from: idea → signal → revenue engine
…much faster than before. And this is exactly where most companies struggle.
Not at raising. But at catching up. So, isn’t “revenue doesn’t matter.”
It’s this:
There is no magic number that unlocks seed
Investors care more about how fast you’re moving than where you are
The real game starts after you raise, not before
Because today, raising a seed round is increasingly accessible.
Earning your Series A is not.
The AI categories VCs are overpaying for right now.
PitchBook’s 2026 Artificial Intelligence Outlook flags a clear warning: some of the most hyped AI subsectors today are also the most vulnerable to capital destruction.
The common pattern across these areas isn’t a lack of demand; it’s too much sameness.
What’s overheating right now

AI code generation
So-called “vibe coding” startups built on top of large language models have exploded in traction and funding. Cursor hit $100M ARR in just 12 months.
Cognition doubled revenue in a single quarter. That success pulled in waves of copycats, many offering marginal improvements on the same underlying models. As more capital chases the same workflow, differentiation collapses fast.
Autonomous driving software
Self-driving AI remains capital-intensive, slow to commercialize, and heavily regulated. Despite years of progress, timelines remain uncertain and competition is brutal. For many startups, the burn curve is steep while defensibility is thin.
Generative engine optimisation (GEO)
Startups optimising how brands appear inside ChatGPT or Claude resemble early SEO plays but with far less control.
Platforms can change ranking logic overnight, wiping out product value. Analysts see this as especially fragile infrastructure.
Precision medicine AI
AI-driven genomics and diagnostics promise breakthroughs, but face long validation cycles, regulatory risk, and complex go-to-market paths. Capital is flowing faster than clinical proof.
Why this matters
PitchBook analysts point out that these sectors share a dangerous trait:
lots of startups, little structural differentiation, and heavy dependence on foundation models they don’t control.
When markets crowd this tightly, outcomes don’t average out they skew toward a few winners and widespread losses.
For founders & VCs
AI isn’t overheated everywhere. But in crowded, obvious categories, the window for undifferentiated entrants is closing fast. Future winners will be defined less by “AI inside” and more by distribution, proprietary data, workflow lock-in, and real switching costs.
In the next cycle, value won’t be destroyed quietly; it will be written down all at once.
SOMETHING MORE
🧩 Frameworks & insightful posts
The Billion-Dollar Founder Study: What 20 years of unicorns say about who you should build with.
There’s a very common belief in startups: the best companies are built by people who already know each other well - friends, ex-colleagues, college roommates. It feels logical. Trust is already there, communication is easier, and things move faster in the early days.
Andy Chen and Amy Lin (from Outcast Venture) decided to actually test this idea by analysing 20 years of $1B+ startup exits, manually reconstructing how founding teams were formed. And what they found challenges a lot of what founders assume.
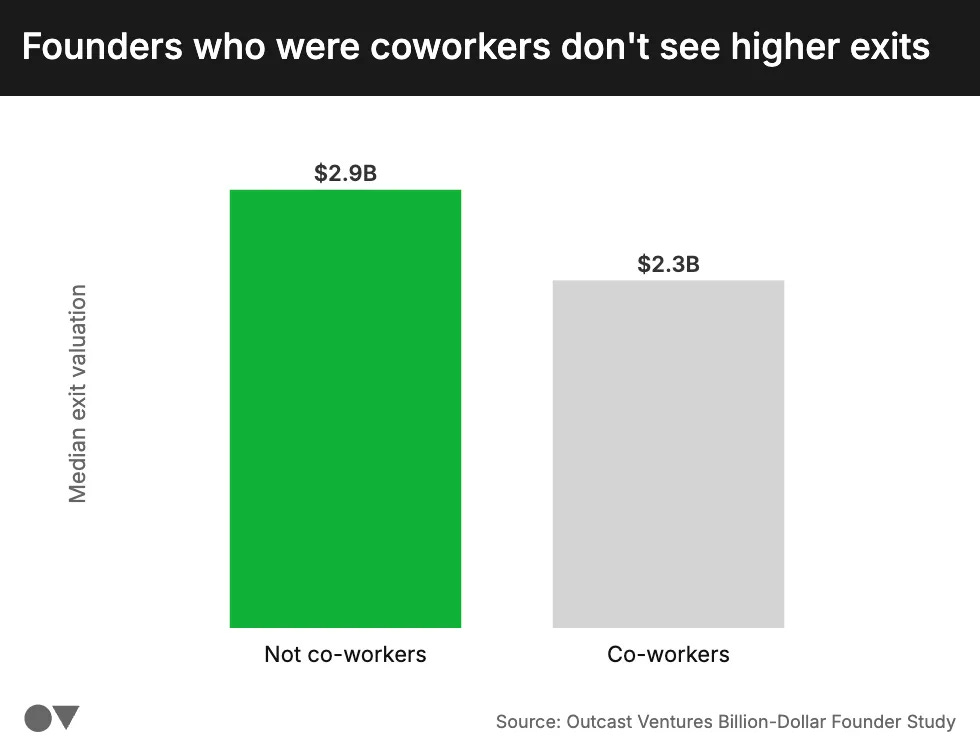
Working together before doesn’t actually lead to bigger outcomes.
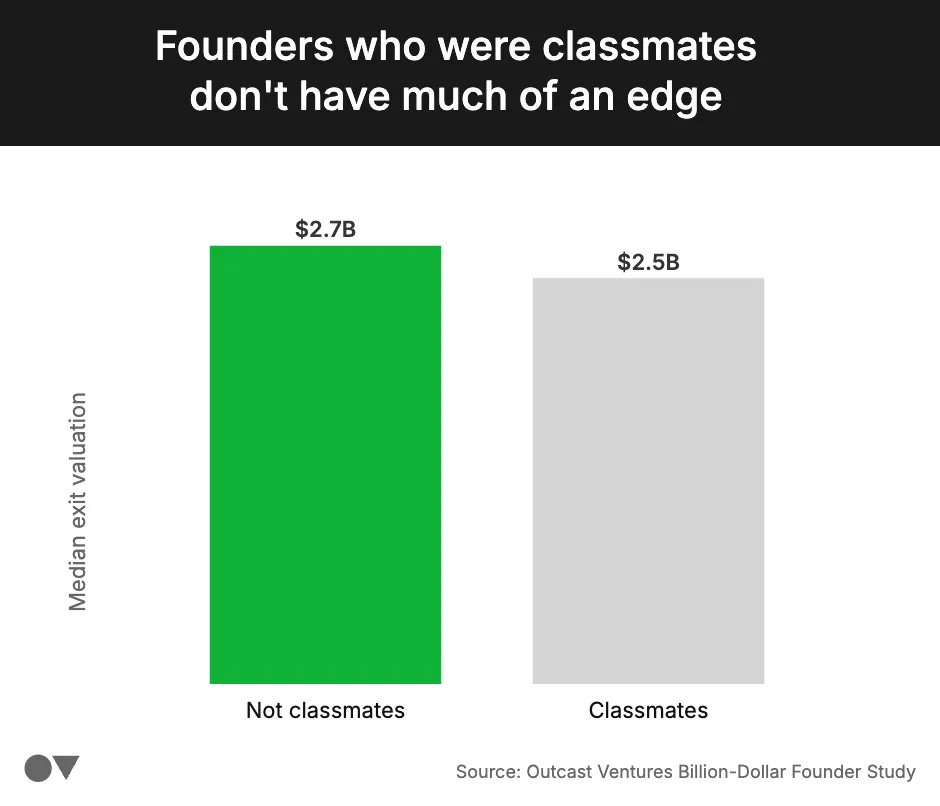
Founders who had prior working relationships ended up with lower median exit values compared to those who didn’t. The same pattern shows up with school connections as well. These relationships help you get started, but they don’t give you an edge where it really matters - during scale.
Prior work relationship → ~$2.3B median exit
No prior relationship → ~$2.9B median exit
Same-school founders also show slightly lower outcomes
What this suggests is simple: familiarity reduces early friction, but billion-dollar companies are not decided in the first year. They’ve decided over a decade of building, hiring, and navigating completely new problems.
That’s where a different factor starts to dominate -complementarity.
The best teams aren’t the most comfortable ones. They’re the ones where skills, thinking styles, and strengths don’t overlap too much. As the company scales, that diversity becomes a real advantage.
You see the same pattern when you look at team structure more broadly.
Most large outcomes are not built by solo founders. While solo founding is increasing (especially post-AI), it rarely shows up in the biggest companies.
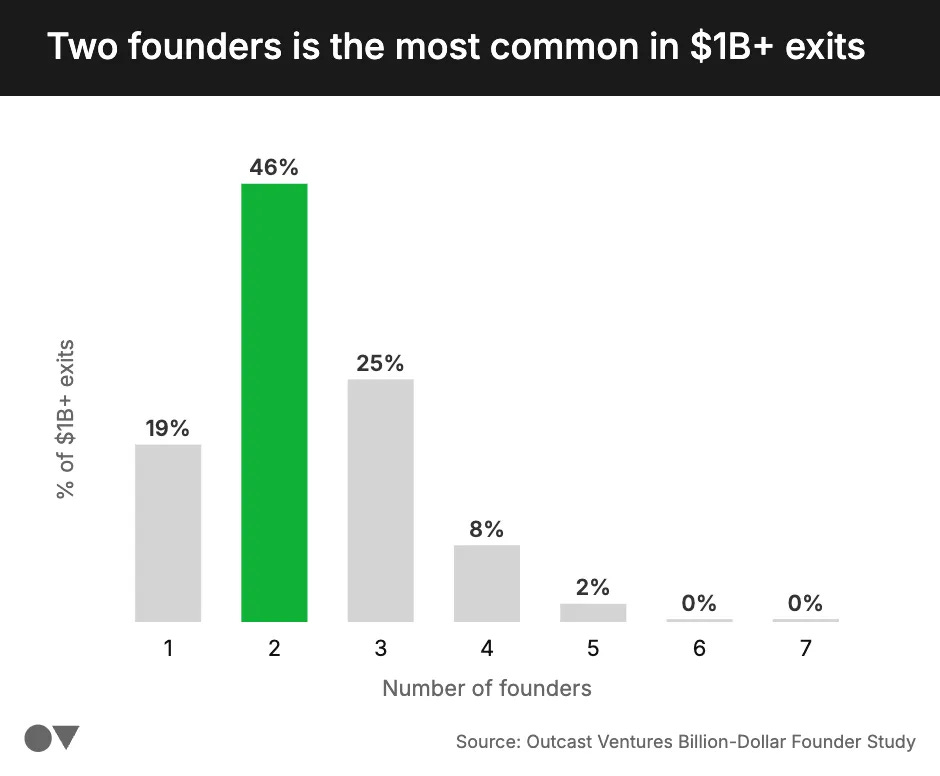
82% of $1B+ companies had multiple founders
Solo founders account for ~20%, but almost disappear in top-tier outcomes
Solo companies also take ~3 years longer to reach exit
Starting alone is clearly possible. But sustaining and scaling complexity over 10+ years is where teams outperform.
Another strong signal in the data is experience.
Founders who have been through the startup cycle before - especially those who have already built or exited a company- consistently produce larger outcomes. The gap is meaningful.
CEOs with prior startup experience → ~41% higher median exit
Teams with at least one prior exit → nearly 2x higher valuations
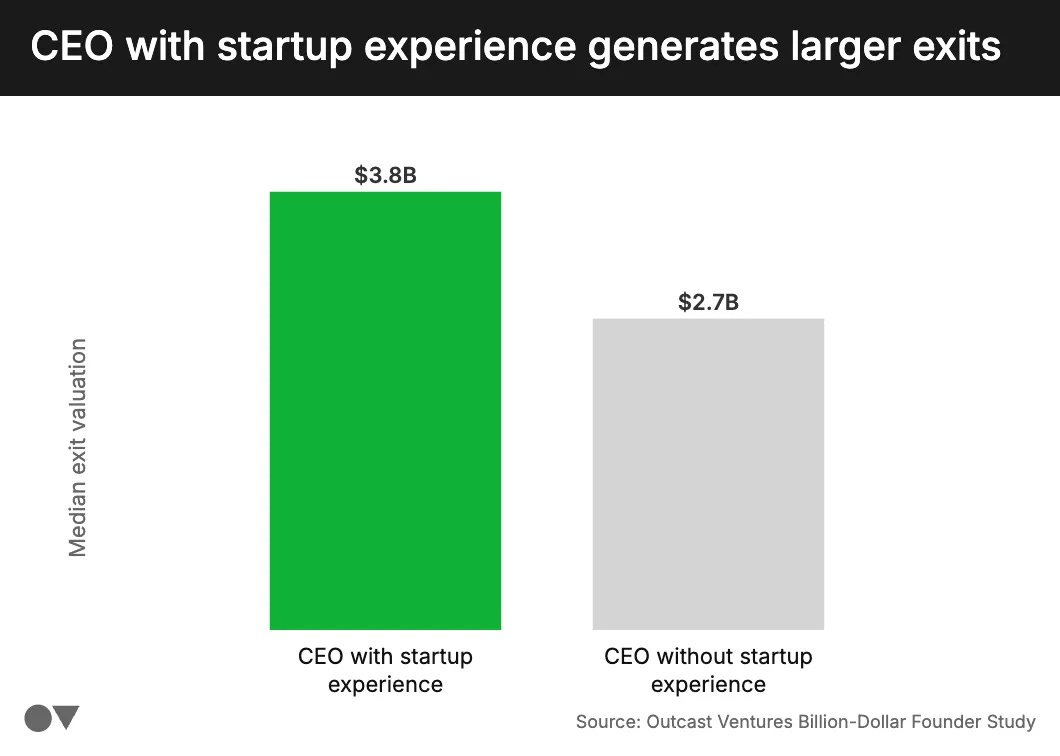
This makes sense when you zoom in. Scaling a company isn’t just about product or vision. It’s about hiring at speed, managing investors, navigating downturns, and making decisions under uncertainty. Founders who’ve done it before simply recognize patterns faster.
Time is another underestimated variable.
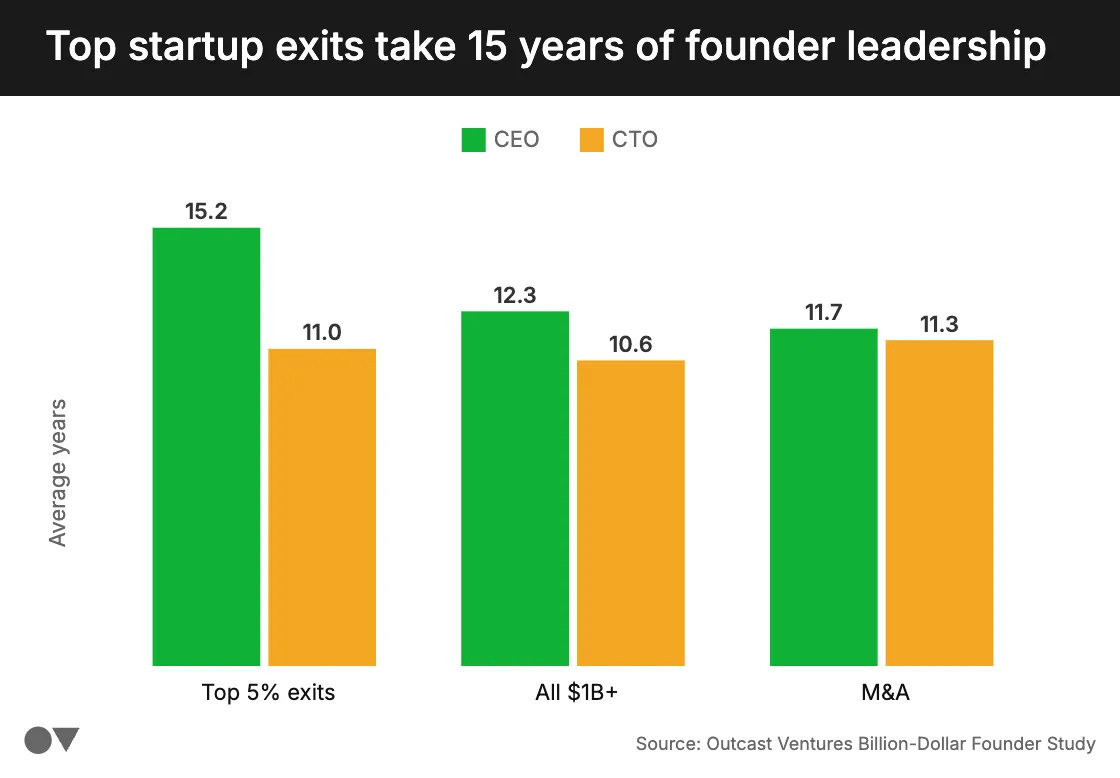
Most founders think in 3–5 year horizons. But the data shows something very different.
The median time to a billion-dollar outcome is around 12 years, and the largest outcomes often take even longer. Founding CEOs typically stay for a decade or more, which means the real job isn’t launching - it’s continuously rebuilding the company as it grows.
Even the founder's age reflects this dynamic. The median age is around 35—not extremely young, not too late, but more importantly, it aligns with timing.
The biggest outcomes tend to come from founders who hit their prime during major platform shifts.
1980s-born founders → mobile and cloud
1990s-born founders → now benefiting from AI
So it’s not just about who you are. It’s about when you build.
What’s interesting is what doesn’t matter as much as people think.
Elite schools show up frequently in founder lists, but they don’t correlate with larger exits. Family founding teams are extremely rare. Even long-standing relationships between founders don’t translate into better outcomes.
The pattern across all of this is surprisingly consistent.
Big companies are not built by the most obvious or convenient teams. They are built by small, complementary groups of people who bring different strengths, have some level of experience, and are able to endure and adapt over a long period of time, often aligned with a major technology wave.
The takeaway is simple, but most founders ignore it: Don’t optimize for who feels easiest to start with. Optimize for who you can build with for the next 10–15 years.
Are you overpaying your first hire with equity without realising it?
One of the easiest ways founders quietly mess up their cap table is very early. The first few hires feel equally risky, equally important, and emotionally, you want to treat them the same. But real data shows that equity should drop much faster than most founders expect.
This insight comes from Jason Lemkin, based on Carta’s State of Seed data covering ~50,000 startups. And the pattern is sharper than most pitch-deck math assumes.
Here’s the part most founders miss: only your very first hire truly belongs in the “founding team economics” bucket.
Everyone after that moves into a different risk-reward zone much faster than intuition suggests.
What the data actually shows when you zoom out.
Your first hire sits at a median of ~1.5% equity. That already feels lower than what many founders assume. But the real surprise is what happens next.
The second hire drops to ~0.85%. By hire #3, you are already around ~0.5%. By hire #5, the median is ~0.33%.
This is not a gentle slope. It is a cliff.
In practice, this means:
The equity drop from hire #1 to hire #2 is about 43% for the very next person who joins.
Only the very first hire reliably crosses the 1% mark at the median.
By the fifth hire, you are already in what investors mentally bucket as normal early employee equity.

Why this matters more than founders think.
Most early cap table damage doesn’t come from one huge mistake. It comes from flattening this curve. When founders give 1-1.5% to multiple early employees, they unknowingly burn future flexibility.
Later, when you need to hire a VP of Engineering or CFO at Series A or B, those roles often need meaningful equity. And suddenly, there is nowhere clean for it to come from without painful reshuffling.
There’s also a psychological angle here. The first hire is taking an existential risk. They are joining when there is no product, no traction, and often no salary stability. Hire #4 or #5 is joining something that already exists. The data reflects that reality, even if founders emotionally don’t.
A quick note on advisors, because this is where founders often leak equity quietly.
Advisor equity is dramatically lower than what most founders assume. At the seed stage, the median advisor grant is around ~0.12%. Only the top 10% of advisors cross 0.5%, and almost nobody should touch 1% unless they are delivering something truly existential.
A useful gut check:
If this advisor disappeared tomorrow, would your company materially suffer in the next 6 months? If the honest answer is no, they should not be anywhere near 1%.
So, think of early equity as a decaying asset. It loses value fast as certainty increases. Treat your first hire as a special case, because they are. But do not let that logic spill over to hires two through five.
If you want a simple mental model:
Hire #1 is almost a co-founder substitute.
Hire #2 is a major early bet, but already less so.
Hire #3 onward is execution talent, not existential risk-taking.
The data doesn’t tell you what is right for your company. But it does tell you what normal looks like. And most founders who regret equity decisions later regret being too generous too early, not the other way around.
Use this as a calibration point before you send that next offer letter.
You can also check out out Equity dilution decisions: ownership, control, and negotiation guide for founders.
Are waitlists still worth building in 2026: a16z Guide?
A few years ago, a waitlist meant hype. Ship a landing page, tweet a demo, collect thousands of emails, feel good. Today, that playbook is mostly broken. Attention is harder, inboxes are crowded, and “cool idea” signups rarely turn into revenue.
This shift was neatly unpacked by a16z speedrun in their breakdown on modern waitlists, and the core idea is simple but uncomfortable: a waitlist isn’t a vanity metric anymore. It’s a filter.
The founders who are winning in 2026 are using waitlists as a quality control system, not a popularity contest.
Here’s what actually matters now.
In the past, founders obsessed over list size. Today, the only thing that matters is what happens after someone joins.
Research shows that if you invite users within a month, waitlist-to-paid conversion can hit ~20%. Wait longer than three months, and it often drops below 10%. Big lists decay fast. Waitlists rot if you don’t activate them.
So the real question founders should be able to answer isn’t “how many people signed up?” It’s:
Who exactly joined
Why did they join now
What problem do they think you solve
And how many of them will actually take the next step
Anything else is just noise.
What does doing it right look like in practice?
The best founders now design waitlists backwards from intent.
Take Day AI. They didn’t launch early. They waited until they had a crisp story, then created a single “spike moment, a coordinated announcement across press, owned content, and social. Everything pointed to one conversion surface: the waitlist. The result wasn’t just volume, it was alignment with their sales capacity.
Another smart pattern came from Paid AI. They treated the waitlist as an intent ladder, not a dead end. Instead of stopping at an email, they progressively asked for more commitment:
email
role/industry context
booking a call
eventually, money

This is the key mental shift: your waitlist should qualify users, not just store them. Cash, even a small amount, is the strongest signal you’ll ever get.
And if you’re building hardware, this matters even more. Taya didn’t ask people to “stay tuned.” They asked for preorders. Real money. On launch day, they sold one unit every four minutes. That did two things at once: it validated demand before manufacturing, and it revealed exactly who the real customers were. That insight shaped everything that followed, from messaging to roadmap.
So a waitlist is no longer about hype signalling. It’s about learning faster and de-risking earlier. It should tell you who is serious, what they’re willing to do next, and how quickly you can move them forward.
If your waitlist can’t help you prioritise, segment, invite quickly, and measure conversion, it’s not an asset; it’s a distraction.
Build your waitlist like a machine, not a mood board.
NEWS RECAP
🗞️ This week in startups & VC
New In VC
Gateway Capital Partners, a Milwaukee-based venture firm founded by Dana Guthrie, has announced the first close of its $25M Fund II. (Link)
Sonder Capital, a San Carlos, CA-based healthcare venture capital firm investing in companies enhancing the standard of care, closed its second fund, Futures II. (Link)
Overmatch Ventures, an Austin, TX-based early-stage venture capital firm investing in deeptech, defensetech, and spacetech, closed its second fund at $250m. (Link)
New Startup Deals
Gander Robotics, a Cambridge, MA-based autonomous rescue systems company, raised $1.1M in Pre-Seed funding. (Link)
estaie, a Dubai, UAE-based hospitality tech startup, raised a 7-figure Pre-Seed funding round. (Link)
Whirl AI, a San Francisco, CA-based enterprise AI company, raised $8.9M in Seed funding. (Link)
Linx Security, a NYC-based identity security company, raised $50M in Series B funding. (Link)
Oncomatrix, a Derio, Spain-based biopharmaceutical company, raised $67M in funding. (Link)
Centivax, a South San Francisco, CA-based biotech company, raised $37M in funding. (Link)
daydream, a San Francisco, CA-based AI-native search agency, raised $15M in Series A funding. (Link)
TODAY’S JOB OPPORTUNITIES
💼 Venture capital & startup jobs
All-In-One VC Interview Preparation Guide: With a leading investor group, we have created an all-in-one VC interview preparation guide for aspiring VCs. Don’t miss this. (Access Here)
Associate - Lightbank | USA - Apply Here
Associate - Climate Venture Fund | USA - Apply Here
Senior Investment Analyst - Earth Foundry | USA - Apply Here
Ventures Analyst/Associate - Plug and Play Tech Centre | USA - Apply Here
Research Innovation Program Director - Generator | USA - Apply Here
Investment Analyst Intern - NAV Capital | Dubai - Apply Here
Finance Associate - RA Capital | USA - Apply Here
PE & VC Partner Manager - Dealhub | UK - Apply Here
Investment Analyst - Lunicorn Venture | UK - Apply Here
Program Manager - a16z | USA - Apply Here
Associate or Senior Associate - AI - BVP | USA - Apply Here
Venture Fellow - age1 | USA - Apply Here
Venture Capital Associate - Sky9 Capital | USA - Apply Here
Investment Summer Associate - AI Tooling - M13 | USA - Apply Here
Event Marketing Manager - AI Fund | USA - Apply Here
PARTNERSHIP WITH US
Get your product in front of over 115,000+ audience - Our newsletter is read by thousands of tech professionals, founders, investors and managers worldwide. Get in touch today.
🔴 Share Venture Curator
You currently have 0 referrals, only 5 away from receiving a 🎁 gift that includes 20 different investors’ contact database lists - Venture Curator
This is such a crucial point. Are we prioritizing innovation over responsibility? How do we ensure that the benefits of AI reach everyone, especially those impacted by its shortcomings? Shouldn't we invest in research and education alongside building the tools?