

👋 Hey, Sahil here - welcome to today’s edition of Venture Curator, where we break down how great startups grow, how top investors think, and what’s shaping the future of tech.
P.S. Get access to 100+ startup & VC resources, investor databases, fundraising templates, 150+ premium archive posts and exclusive startup research - all in one place.
FROM OUR PARTNER - SEMRUSH
Your customers are searching on Google AND ChatGPT. Can they find you on both?
Search has changed. Ranking on Google still matters, but buyers are also asking AI tools which products to use, which companies to trust, and how different options compare.

Semrush One brings both sides into one place. You can track your Google rankings and AI mentions, see the prompts driving demand, compare your visibility against competitors, and find gaps you can actually act on.
It monitors 239M+ relevant LLM prompts globally, alongside the SEO data Semrush is already known for.
Partnership With Us
Get your product in front of an audience of 125,000+ - Our newsletter is read by thousands of tech professionals, founders, investors and managers worldwide. Get in touch today.
📜 DEEP DIVE
What does a VC really write in their internal notes after they reject you? (Most founders never see it).
There’s probably a VC rejection sitting in your inbox right now. Most founders have at least one.
It’s three or four sentences long. Warm, a little apologetic, and with nothing in it you can act on. “Really enjoyed the conversation. It’s a bit early for us at this stage. Would love to stay close as you grow.”
You’ve likely read it more than once, looking for the line that tells you what went wrong. It isn’t there, and it never was. That email had one job, which was to end the conversation politely, and it did that job well.
But it wasn’t the only thing written about you that day. When a fund passes, a second record goes into its system: a reason code, a short note, and often a date. That one isn’t meant for you, and most founders never see it. It’s written so that a colleague who has never met you can open your file eighteen months from now and know exactly what to do with it.
So while you’re reading the email, the firm is working from the note.
Most passes aren’t verdicts
Here’s the part that should change how you read every rejection you’ve had.
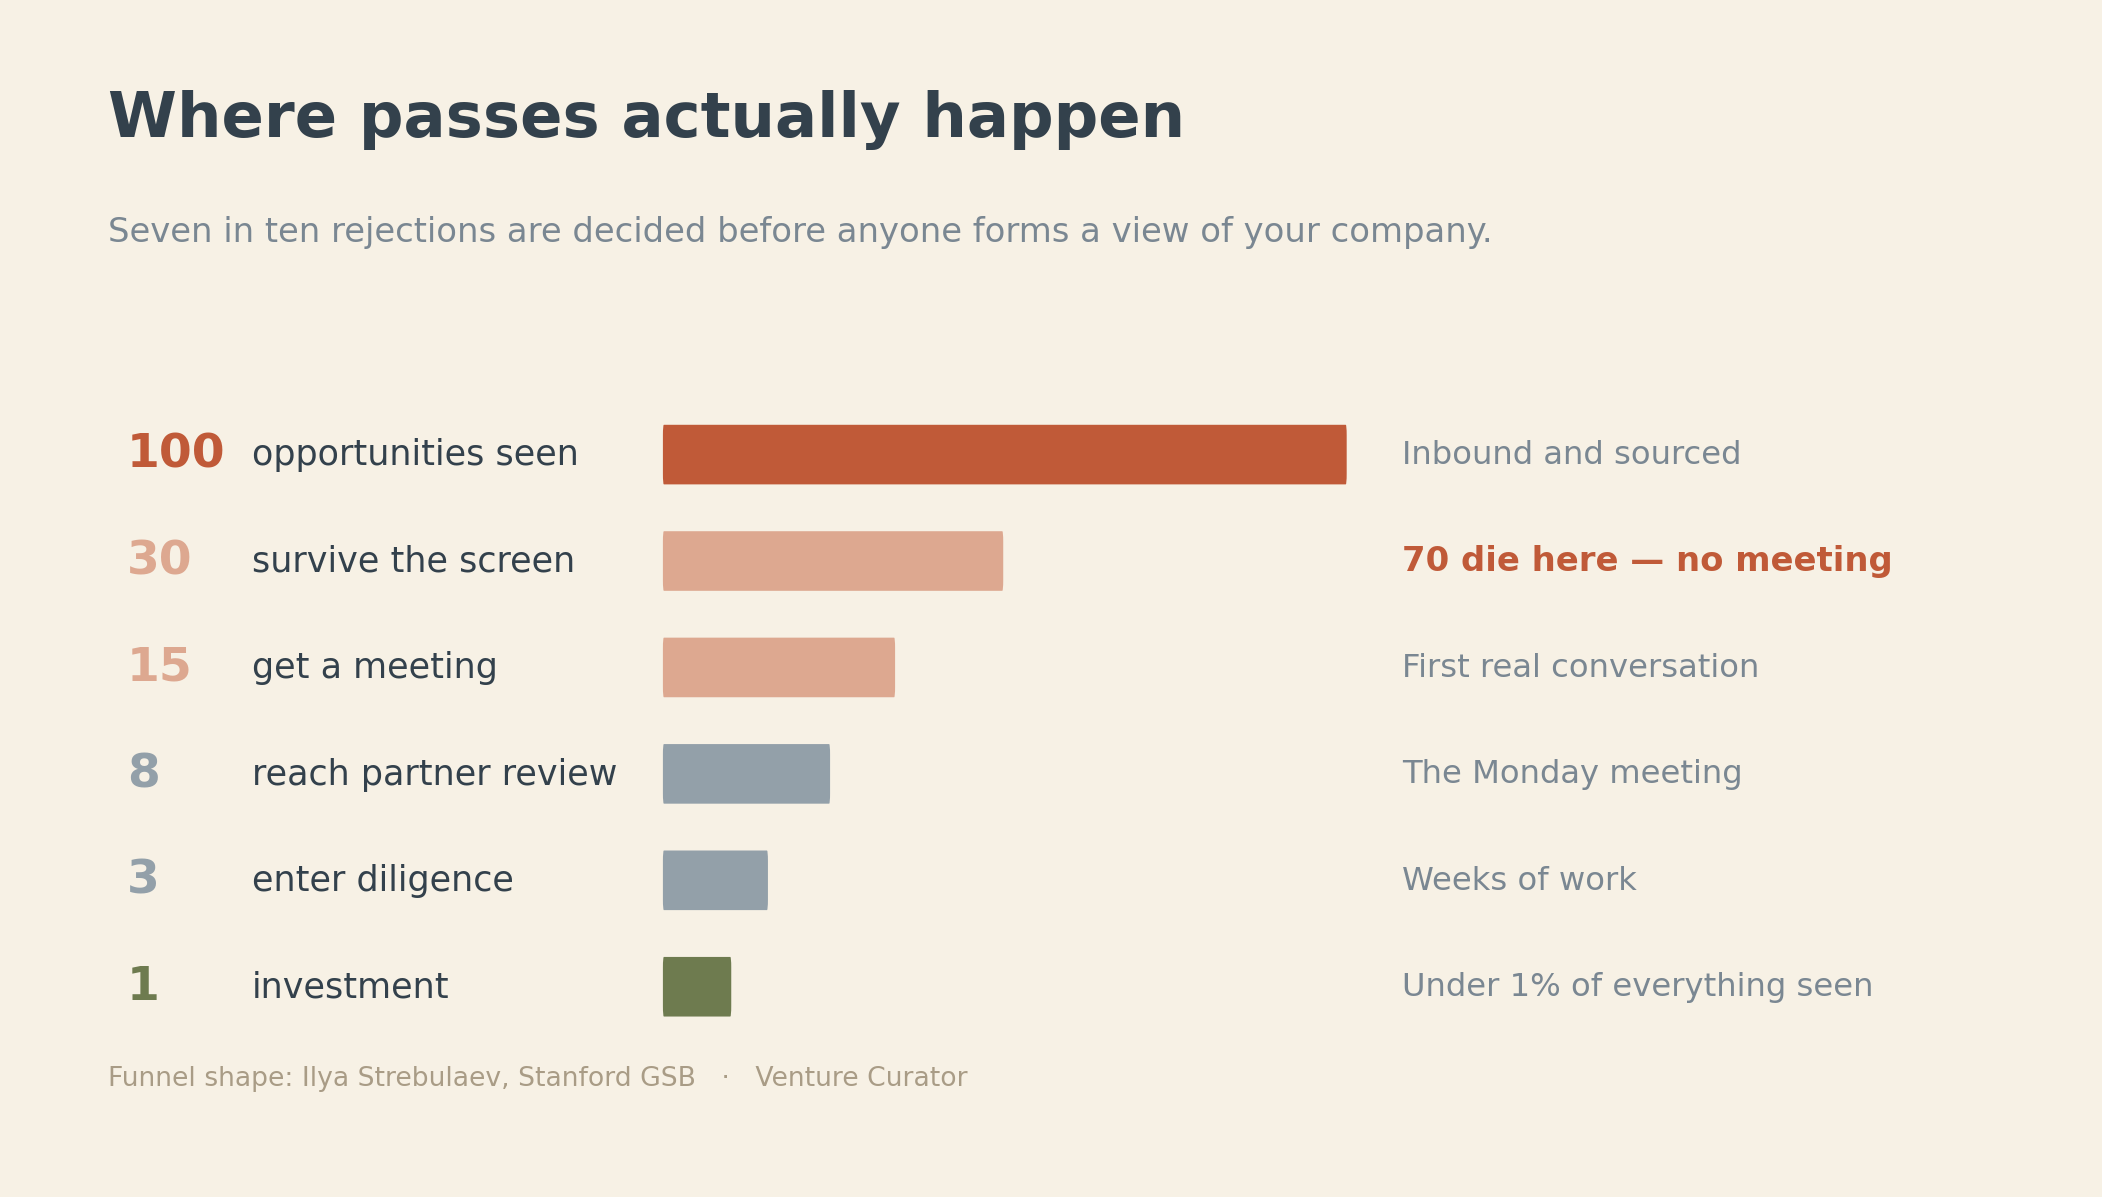
Stanford’s Ilya Strebulaev has spent a decade studying how VCs actually make decisions, and he describes the funnel plainly: roughly 70 of every 100 opportunities die at the first screen, usually within minutes and without a single meeting. From first contact to a signed cheque, conversion runs around 1% at Homebrew and 0.7% at a firm like a16z.
Now think about your own inbox. If seven in ten deals are cut before anyone talks to the founder, then most of the passes you’ve collected were never really judgements on your company. Nobody formed a view. There was no evaluation for you to fail.
A pass, in other words, is the default. It’s what happens when nothing pushes a deal forward. On its own, it tells you very little. What does tell you something is which kind of pass you got, and that information exists. It’s just sitting in their system instead of in your inbox.
The mistake this leads to
Founders treat every pass as feedback, so they go and change something.
They rebuild the deck. They rewrite the market slide. They wait for a metric to move before they go back out. Sometimes they change the company itself, pivoting because of a pattern of rejections that had nothing to do with the product.
And the pattern is real, in a way. Twenty funds did say no. But if fifteen of them cut you at the screen because of stage, sector, geography or cheque size, then what you’re looking at is a pattern in your target list, not in your business.
The useful signal sits in the handful of passes that came after real work: the ones where a partner spent hours on you, took you to a Monday meeting, maybe started calling references. Those are verdicts, and they carry real information.
The trouble is that you can’t tell the two apart from the outside, because the email looks exactly the same either way. That’s deliberate. The same three sentences go out whether they spent four minutes on you or four weeks.
So the skill isn’t collecting fewer passes. It’s learning to read the ones you get.
What’s inside today’s deep dive
What’s actually in the record? The four fields a firm keeps on a passed deal, and which one decides whether you ever hear from them again.
Why is the reason you’re given never the reason that’s written? The internal note has a different audience, and a different job.
What do the eight standard phrases actually mean? Each one decoded, with the tell that separates the polite version from the real one.
Which passes can be re-opened, and which are permanent? Three categories. Only one of them is worth your energy.
What do you say back? The two-line reply that gets a real answer roughly a third of the time and why the obvious version of that question never works.
How do you get back in eighteen months later? The trigger their system is actually waiting for.
Plus the pass decoder - all eight phrases, what’s written, and what to do and the audit to run on every rejection you’ve already collected.
Let’s get into it.